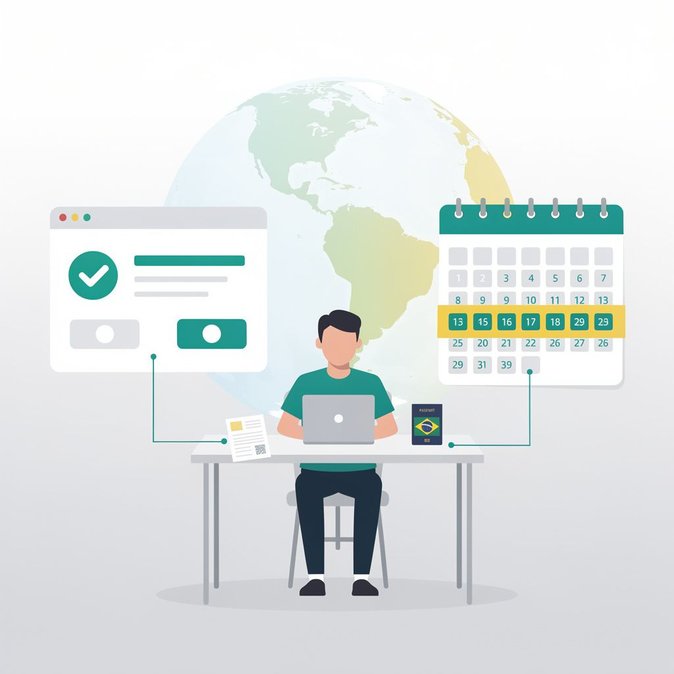
Expat.com has published a comprehensive update (22 October 2026) to its Brazil guide for digital nomads, reflecting recent procedural changes introduced by the Ministry of Foreign Affairs and the Ministry of Justice. The article confirms that, as of 1 September 2026, consulates can issue Temporary Visa XIV (VITEM XIV) electronically to nationals who are already exempt from Brazil’s visitor visa, allowing applicants to upload documents and receive the visa by e-mail without submitting their passport. The guide clarifies financial thresholds—proof of foreign income of at least USD 1,500 per month or a bank balance of USD 18,000—and reminds applicants that the visa is strictly for remote work performed for a non-Brazilian employer. For multinational companies, this removes earlier ambiguities around whether service-contract freelancers qualify: the update notes that freelancers may apply provided they present client invoices and international bank statements. A key compliance point is tax residence. The piece underscores that spending 184 days (consecutive or not) within any 12-month period turns the nomad into a Brazilian tax resident, triggering monthly Carnê-Leão filings on worldwide income. HR and global mobility teams must therefore coordinate with assignees to track days in country and provide guidance on double-tax treaties and foreign-tax credits. The article also lists practical tips—such as apostille and sworn-translation requirements, average internet speeds by provider (Vivo tops the list at 155 Mbps upload), and registration deadlines with the Federal Police. These details help mobility managers create realistic timelines: although the Ministry of Justice targets a 30-day decision time, missing documents pause the clock and applicants then have 30 days to cure defects, potentially doubling overall processing time. Why it matters: Brazil’s rapid shift to e-visas reduces lead times for remote-worker deployments and makes the country more competitive with regional hubs like Costa Rica and Argentina. However, the hidden tax-residence threshold and the need for sworn translations can still derail plans. Companies should update their policy playbooks to capture: 1) electronic-filing checklists; 2) day-count tracking tools; and 3) trigger points for tax briefings once an assignee approaches the 150-day mark.
Source: Expat.com